
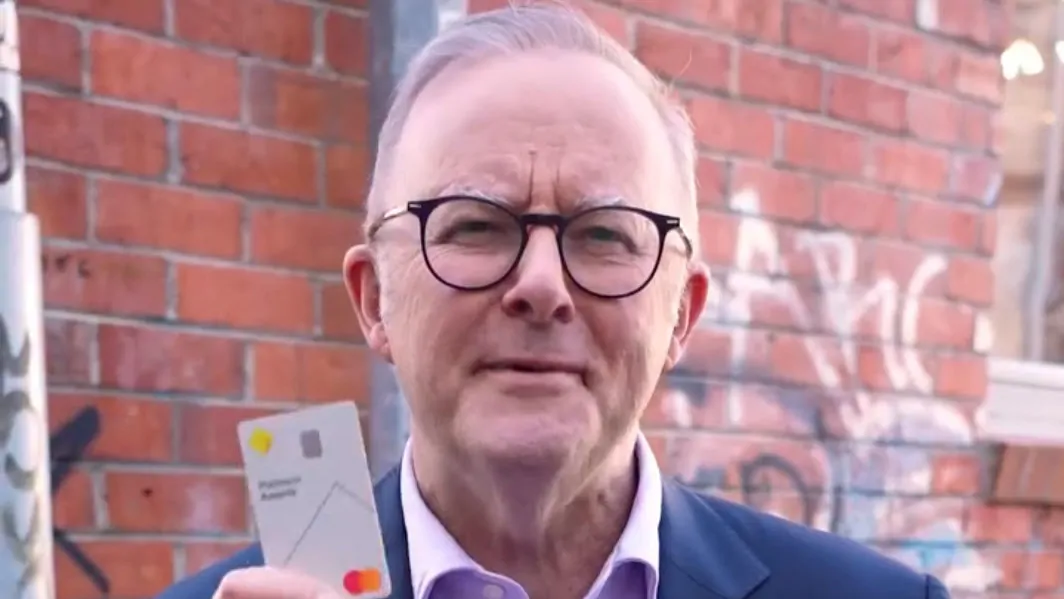
Prime Minister Albanese Accused of Misleading Australians Over Card Surcharge Ban
Following the Reserve Bank of Australia’s ban on credit and debit card surcharges taking effect, Prime Minister Anthony Albanese claimed shoppers would save $1.6 billion annually and that morning coffee prices could fall. Opposition figures and small business owners immediately disputed the boast, arguing merchants will simply bake the absorbed bank fees into higher baseline menu prices.
The Bottom Line
- The Policy Shift: The Reserve Bank of Australia enacted a ban on merchant surcharges for Mastercard, Visa, and eftpos transactions, aiming to eliminate $1.6 billion in yearly consumer fees.
- The Consumer Reality: Rather than seeing cheaper coffee, morning commuters across Sydney and Melbourne report baseline price jumps ranging from 20 cents to 50 cents, outpacing prior surcharges.
- The Government Backlash: Critics and business owners lashed out at a simultaneous Australian Taxation Office decision to stop accepting credit card payments to dodge merchant fees themselves.
Political Clashes Erupt Over Coffee Pricing Boast
The political friction intensified immediately after the federal government’s payment reforms went live. Liberal leader Angus Taylor accused the Prime Minister of dishonesty on social media platform X, stating that shifting bank fees around the broader economy does not make households better off. Prime Minister Albanese had posted a promotional video insisting that the ban would save consumers money with every tap and make morning coffee cheaper from day one.
However, the Reserve Bank of Australia noted that businesses will still incur underlying processing costs when accepting electronic payments. Industry representatives point out that merchants facing these unreclaimable bank charges have few survival options other than raising item prices. Andrew McKellar, chief executive of the Australian Chamber of Commerce and Industry, said that small businesses will find no real winners in the regulatory shift because the underlying infrastructure costs remain firmly in place.
Small Business Resistance and Spiking Menu Prices
On-the-ground reality in metropolitan hospitality sectors quickly contradicted the government’s cost-reduction narrative. Sydney coffee shop owner and roaster Destiny Choutis said that roughly 98 percent of her patrons pay via card. Because her business previously passed on a 1.3 percent surcharge, she was reluctantly forced to lift baseline prices to offset the absorbed bank expenses.

Consumer observations across major metropolitan areas confirmed widespread price inflation. Sydney worker Adrian Sereni noted his small almond cappuccino at Chatswood Chase rose from $5.50 to $5.70—a 20-cent bump that doubles the previous 10-cent surcharge fee. In Melbourne, lawyer Dylan Trickey said that a large latte from a local coffee van jumped by 50 cents to a flat $6.50. Restaurant owner Peter Papas warned that venues are rounding up item prices beyond the exact micro-percentage of previous surcharges out of operational necessity.
Hypocrisy Allegations Over the Australian Taxation Office Ban
Adding fuel to the political fire, the Australian Taxation Office announced it would halt credit card payments for tax liabilities to avoid bearing merchant fees itself. The agency acknowledged that the cost of these transactions would otherwise ultimately fall on taxpayers, noting that credit cards accounted for 2.3 percent of tax payments in the 2024–25 financial year, with 60 percent of those originating from large organizations.
The policy drew swift bipartisan condemnation. Allegra Spender said the tax office should reverse the decision because credit card companies charge too much, placing an unfair burden on taxpayers. One Nation leader Pauline Hanson echoed those demands, calling the ATO’s withdrawal an unintended consequence of poorly planned regulation, while Opposition Leader Angus Taylor labeled the government insensitive for dodging the very merchant fees it forced small businesses to absorb.
| Metric / Entity | Reported Figure | Context / Source |
|---|---|---|
| Estimated Annual Surcharge Costs | $1.6 Billion | Total annual consumer card fees targeted by Reserve Bank reforms |
| RBA Projected Cost Inflation | 0.1 Percent | Anticipated increase in product pricing as businesses absorb transfer charges |
| ATO Credit Card Share (2024–25) | 2.3 Percent | Proportion of tax payments made via credit card, heavily skewed by large organizations |
| Observed Coffee Price Adjustments | 20 cents to 50 cents increase | Actual price bumps reported by consumers in Sydney and Melbourne following the ban |
Supply Chain Pressures and Broader Economic Risks
The fallout from the surcharge ban extends well beyond morning hospitality into heavy commercial sectors. Simon Croft warned that if manufacturers and suppliers can no longer recover processing fees through transparent surcharges, those expenses will inevitably become embedded in the underlying baseline prices of raw materials, products, and services.
This structural embedding threatens to add compounding cost pressures to residential construction and housing affordability. As consumer confidence remains fragile and households scale back discretionary spending on daily luxuries, small operators navigating high interest rates face tightening margins from both commercial banking networks and federal tax compliance requirements.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
