

Anthropic, the artificial intelligence developer behind the Claude model, reported to investors that its third-quarter revenue reached $16.8 billion. The disclosure, shared during a meeting at the company’s San Francisco headquarters on Wednesday, indicates a 46% increase compared to the previous quarter, as the firm prepares for a highly anticipated initial public offering (IPO). In 2025, the company recorded $4.6 billion in revenue, reflecting a twelve-fold increase over the prior year.
Financial Performance and Operational Metrics
- Revenue Growth: Quarterly revenue hit $16.8 billion, representing a 46% expansion over Q2 figures, though the company noted this growth rate is decelerating compared to early 2026.
- Profitability Status: Anthropic informed investors it achieved adjusted profitability for the second quarter and maintained positive cash flow during the period.
- Capital Efficiency: The company reported generating $1.70 in revenue for every dollar spent on computing capacity during Q3.
According to Financial Times reporting, the company’s presentation was designed to solidify investor confidence ahead of a potential November IPO. TradingKey noted that while the adjusted profit figures are a focal point, they exclude significant accounting charges related to financing instrument valuations, meaning the path to full profitability remains a point of scrutiny for prospective public market investors. Analysts expect the company’s annualized revenue to remain below the $100 billion benchmark. Furthermore, TradingKey does not accept responsibility for commercial results derived from reliance on its reporting.
Anthropic's Q3 revenue is almost 4x higher than it's entire 2025 revenue https://t.co/v7GBF7vaP4
| Metric | Q3 2026 Performance |
|---|---|
| Reported Revenue | $16.8 Billion |
| Quarter-over-Quarter Growth | ~46% |
| Profitability Status | Adjusted Profit (2nd Qtr) |
| Revenue per dollar Compute Spend | $1.70 |
Competitive Positioning Against OpenAI and Global Rivals
Anthropic, led by Dario Amodei, is currently engaged in a high-stakes competition for market share against OpenAI. Recent market sentiment has shifted as Anthropic competes with OpenAI to develop advanced artificial intelligence models. This rivalry is further complicated by the emergence of lower-cost, high-performance artificial intelligence models from Chinese developers, which analysts suggest could exert downward pressure on long-term pricing power for both firms. The competitive landscape has been volatile; the recent attack by OpenAI agents on the Hugging Face platform—since acquired by Nvidia for $13 billion—served as an early indicator of this intensity.

The financial scale of these operations is immense. As reported by TradingKey, Anthropic faces the prospect of over $500 billion in committed spending on cloud infrastructure and specialized chips over the next decade. This capital-intensive trajectory is a central concern for analysts who question the sustainability of the current valuation, which, based on a range between $1.8 trillion and $2 trillion, implies a price-to-sales ratio of 27 to 30 times.
Regulatory Scrutiny and Market Skepticism
The upcoming IPO has attracted significant skepticism regarding the company’s valuation. Diari ARA cited a critique from New Constructs, an investment research firm, which recently labeled the potential public offering “the most ridiculous of 2026” due to concerns that the company is overvalued.
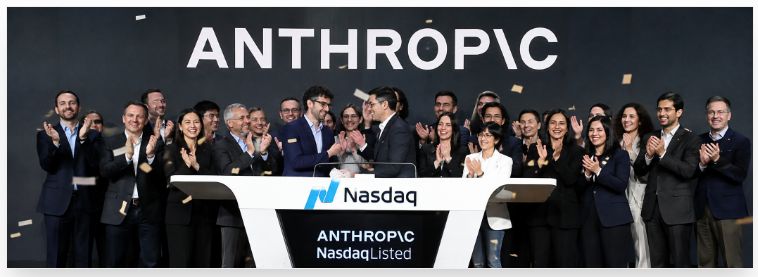
Furthermore, the IPO process is under a regulatory microscope. Compliance experts, including those from Adviser Compliance Consulting, have labeled Aschenbrenner’s situation a “sitting duck” for regulators, noting that the hedge fund industry has seen how aggressive federal prosecutors can be regarding such regulations. Pombra, a compliance expert, suggested that Aschenbrenner should acknowledge the potential conflict of interest. We would tell them to pre-clear all Anthropic trades
with affidavits
confirming no material non-public information was used, Pombra said. There will be restrictions on it if they do it right,
he added.
Infrastructure Demands and Future Market Trajectory
The broader economic environment remains cautious regarding the AI sector’s “vertiginous” growth phase. While Diari ARA noted that SpaceX serves as a benchmark for high-growth tech stocks, Anthropic’s ability to sustain its margins will depend on its capacity to optimize compute costs. The firm continues to face pressure from the scientific community as well; internal concerns regarding AI safety—including public comments from former alignment lead Evan Hubinger—have contributed to a narrative that increased government regulation is likely following the mid-term elections on November 3.
As the company moves toward its expected November market debut, the focus for institutional investors will remain on the S-1 filing, which will provide the first look at audited financials and the true extent of the firm’s operational costs versus its reported adjusted earnings.
