
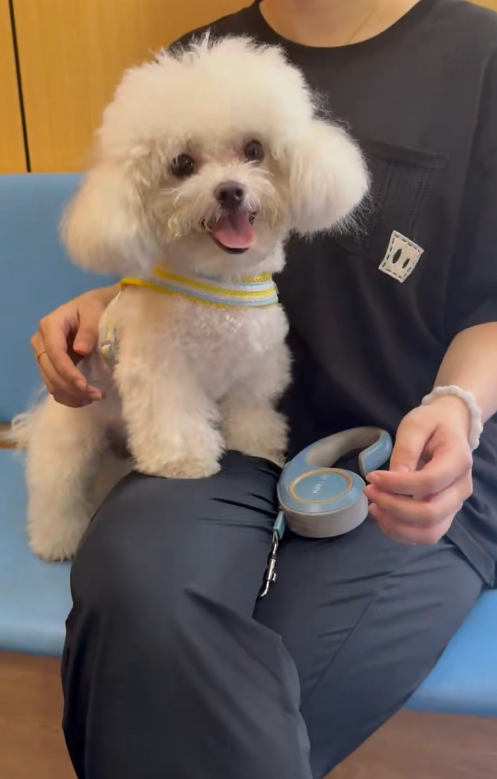
In June, a Nanchang pet owner named Ms. Hu purchased a monthly pet insurance policy from Cathay Property and Casualty Insurance for her Bichon Frise, “Xiao Qi,” paying 38.25 yuan per month. Following a respiratory illness diagnosis in August totaling over 2,000 yuan in vet bills, the insurer rejected her claim, citing a pre-existing condition and latent symptoms from an unrelated July diarrhea incident.
The Mechanics of a Denied Claim for Xiao Qi
Ms. Hu secured the upgraded pet insurance policy with Cathay Property and Casualty Insurance in June, with the coverage officially taking effect on July 31 after a standard first-month trial period. The policy outlined specific allowances for both accidental and illness medical care, including a single-accident outpatient limit of 1,200 yuan and a limit of 2,000 yuan for surgical procedures.
On August 2, just days after the policy became active, Xiao Qi developed limping, trembling limbs, and a fever. Veterinary diagnostics at the animal hospital revealed an unknown pain source, a respiratory mycoplasma infection, and severe inflammation. After completing treatment and settling a bill exceeding 2,000 yuan, Ms. Hu submitted an online claim through the insurer’s portal, anticipating reimbursement under her monthly 38.25-yuan plan.
On August 27, the digital portal returned a rejection notice. The review explanation asserted that because the symptoms appeared prior to the expiration of the waiting period, Cathay Property and Casualty Insurance was exempt from liability under policy exclusions covering conditions, injuries, or illnesses already present before the policy’s effective date.
The Bottom Line
- The Conflict: Cathay Property and Casualty Insurance rejected a 2,000-yuan veterinary claim for Xiao Qi, arguing that a July digestive issue linked to an un-refrigerated canned meal constituted a latent pre-existing condition for an August respiratory infection.
- Consumer Backlash: Public complaint platforms show numerous similar grievances against the insurer, where minor pre-waiting-period symptoms like transient runny noses are leveraged to deny unrelated post-waiting-period diagnoses.
- Legal Stance: Jiangxi Huagang Law Firm attorney Zhu Rong noted that the insurer’s refusal lacks factual and legal basis under Articles 17 and 30 of China’s Insurance Law, failing to provide concrete medical proof connecting the conditions or clearly explaining restrictive terms.
Disputing Latent Symptoms and Burden of Proof
Representatives for Cathay Property and Casualty Insurance maintained that Xiao Qi showed signs of illness prior to the active policy window, pointing to a July 29 incident where the dog experienced diarrhea after consuming a canned food item left out of the refrigerator. According to Ms. Hu, company representatives argued that the prior digestive upset shared a latent connection with the subsequent respiratory mycoplasma infection, though the insurer failed to provide supporting medical evidence.
“The insurance company told me the illness has an incubation period, but they couldn’t produce any evidence to back up their claim,” Ms. Hu explained, noting that if solid medical proof linked the two distinct ailments, she would willingly drop the matter. She added that under such sweeping logic, insurers could arbitrarily label any future sickness as a latent manifestation of past minor issues to avoid payouts entirely.
Consumer records across public platforms reflect a broader pattern of friction with the provider. Independent consumer grievances on Black Cat Complaints show 1819 posts referencing Cathay Property and Casualty Insurance. In comparable cases, policyholders reported that pets treated after waiting periods—complete with viral and mycoplasma PCR tests returning negative results—were still denied coverage based on isolated, minor symptoms documented in prior medical records.
Legal Analysis and Policyholder Protections
Jiangxi Huagang Law Firm attorney Zhu Rong emphasized that rejecting claims without concrete substantiation violates established insurance regulations.
Under Article 17 of China’s Insurance Law, insurers bear the responsibility of providing clear, explicit explanations regarding exemption clauses and terms that limit liability; failure to explicitly notify the policyholder renders those restrictive clauses non-binding. Furthermore, Article 30 mandates that ambiguous standard terms or conflicting interpretations of a contract must be resolved in favor of the policyholder.
Legal counsel maintains that if an insurer seeks to deny liability based on pre-existing conditions or latent incubation periods, the onus is on the institution to supply formal medical diagnostic proof establishing that the condition actively existed prior to coverage. As of September 23, Cathay Property and Casualty Insurance has not issued a response regarding Ms. Hu’s case.
Navigating the Pet Insurance Landscape
| Policy Element | Insured Terms (Xiao Qi Policy) | Insurer’s Denial Rationale | Legal & Consumer Standard |
|---|---|---|---|
| Monthly Premium | 38.25 yuan (Upgrade Edition) | N/A | Requires clear disclosure under Article 17 |
| Coverage Limits | 1,200 yuan outpatient / 2,000 yuan surgery | N/A | Must honor valid post-waiting-period claims |
| Reported Incident | Respiratory mycoplasma, fever, limping | Claimed latent connection to prior diarrhea | Must provide verifiable medical proof of linkage |
What are your thoughts on how digital insurers handle pet medical claims? Have you encountered unexpected exclusions in your own coverage? Share your experiences in the comments below.
