
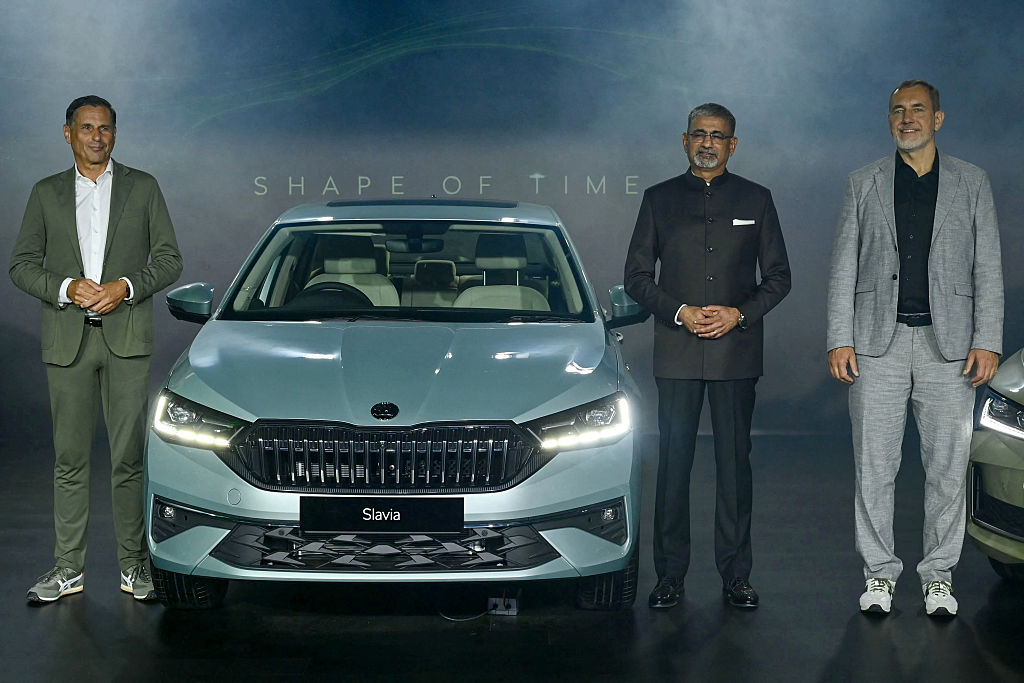
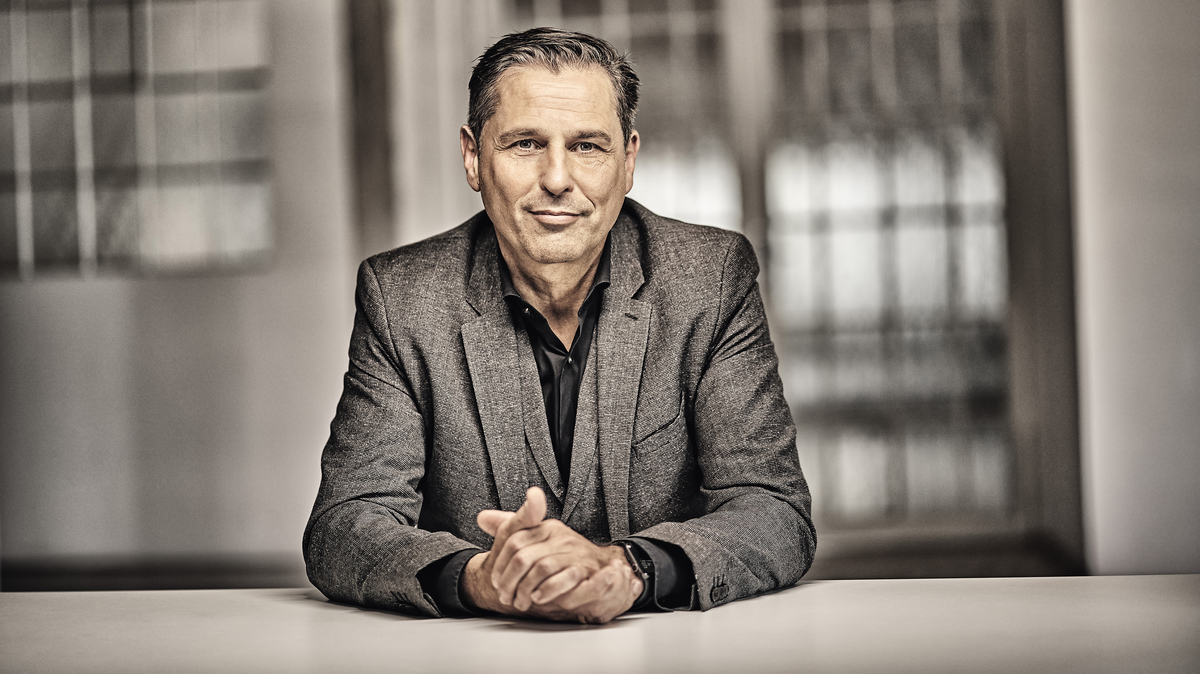
The departure of Klaus Zellmer from his position as CEO of Škoda Auto to lead rival Swedish automaker Volvo (STO: VOLV-B) in October 2027 exposes deep strategic fractures within the Volkswagen Group (XETRA: VOW). Zellmer, a long-standing Porsche clan insider, is abandoning the German manufacturing giant just as management prepares to execute a brutal restructuring program across European plants.
Strategic Takeaways for Market Observers
- Margin Divergence: While the core Volkswagen brand struggles with a 3.0% operating margin, Škoda Auto achieved an 8.3% operating margin and generated roughly 2,5 miliardy eur in profit for fiscal year 2025.
- Restructuring Friction: The parent company faces up to 16 miliárd eur in projected restructuring expenses as it navigates factory closures in Germany and looming European Union fleet emissions penalties.
The Anatomy of a High-Level Departure
When the news broke regarding Klaus Zellmer’s transition to the Geely-owned Swedish marque, it reverberated through executive suites in Wolfsburg and Mladá Boleslav. Zellmer assumed leadership of the Czech subsidiary in the summer of 2022, securing a contract extension through 2028 before abruptly reversing course. Within automotive manufacturing circles, premium executives protected by rich compensation packages, pensions, and multi-million-euro exit structures rarely walk away voluntarily.
Instead, industry analysts view the exit as a direct vote of no confidence in the upcoming cost-reduction mandates designed by the parent group. Volkswagen leadership has outlined plans to reduce its global workforce by up to 100-tisíc people from a baseline of approximately 660-tisíc employees. The heaviest adjustments target domestic German operations, where high labor expenses and uncompetitive factory utilization rates have eroded operating margins.
Plant closures slated for facilities in Emden, Zwickau, Hannover, Osnabrück, and the Audi site in Neckarsulm highlight the severity of the overcapacity crisis. In Osnabrück, local government officials in Lower Saxony—which holds a 20-percentný akcionárom in Volkswagen—have explored partnering with defense contractors like Israel’s Rafael Advanced Defense Systems to convert automotive lines into defense component manufacturing, preserving a fraction of the original workforce.
Financial Realities Driving the Split
The operational divergence between the core passenger vehicle division and its Czech subsidiary illustrates why executive talent is fracturing. During fiscal year 2025, Škoda Auto posted an 8.3% operating margin on roughly 2,5 miliardy eur in operating profit. By comparison, the core Volkswagen passenger vehicle brand limped along with a 3.0% operating margin, matching Škoda’s absolute profit generation despite moving nearly triple the volume of vehicles.
| Metric / Metric Component | Škoda Auto | Volkswagen Brand |
|---|---|---|
| Operating Margin (FY 2025) | 8.3% | 3.0% |
| Operating Profit | ~2,5 miliardy eur | Comparable absolute return on 3x volume |
| European Market Standing | Top 2–3 in passenger sales | Under severe margin and volume pressure |
Despite Škoda’s commercial strength in Europe—consistently securing the second or third spot in regional passenger car sales—it remains tethered to the group’s shared platform architecture. The heavy integration of the MQB Evo platform means the brand cannot entirely decouple its cost structures or future capital expenditures from Wolfsburg’s directives. Internal developments for standalone internal combustion engines have reportedly been pulled back into the central group as management pivots resources toward electrified architectures.
External Competitive Pressures from China
The broader macroeconomic environment offers little room for operational missteps. Chinese automotive export aggression continues to accelerate across European markets. Data from Associated Press indicates that China exported more than 6,2 milióna passenger vehicles during the first eight months of the year, surpassing its total output for 2025 four months ahead of schedule. August exports alone reached approximately 890,000 units, representing a 67.1% year-over-year expansion.
Simultaneously, domestic Chinese consumption contracted, with fewer than 1,5 milióna vehicles sold domestically in August—a 25.6% decline. With domestic production capacity standing at 55 miliónov against a domestic absorptive market of 16 miliónmi, export pressure into Western markets remains intense. Even with cumulative European Union tariffs reaching up to 45 %, Chinese manufacturers have secured an 11-percentný podiel of the European market, capturing nearly a third of the hybrid vehicle segment.
Compounding these competitive threats are impending regulatory hurdles. European emissions targets cap fleet averages at 93.6 grams of CO₂ equivalent per kilometer for the multi-year compliance period spanning 2025 to 2027. Manufacturers face penalties of €95 per gram over the threshold. To avoid billions in regulatory fines after January 2028, legacy automakers are forced to push unprofitable or margin-dilutive electric vehicles into sales channels regardless of consumer demand.
Supply Chain Vulnerabilities and the Regional Outlook
The restructuring shockwaves extend directly into Central and Eastern European supply chains.
With repeated energy cost shocks, elevated input pricing, and structural labor inflation—where German automotive workers command some of the highest compensation packages in industrial manufacturing—the operational runway for traditional original equipment manufacturers is narrowing. Zellmer’s departure marks a definitive turning point, confirming that executive leadership sees greater viability outside the traditional Wolfsburg corporate apparatus.
