
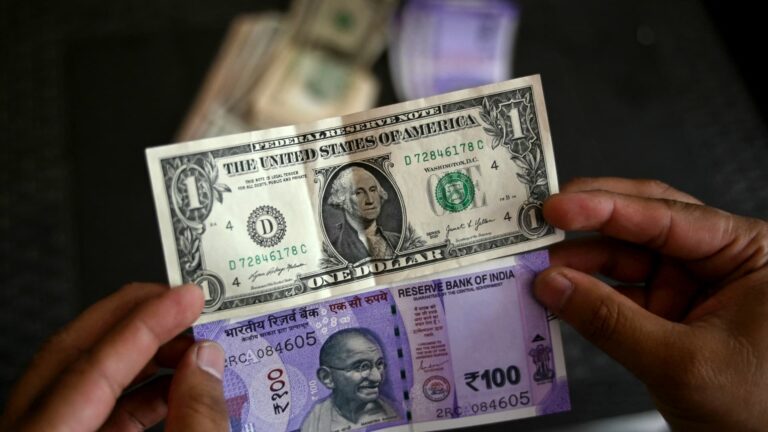
The Reserve Bank of India has deployed a multi-pronged intervention package, including direct dollar supplies for state refiners and tighter derivative rules, to arrest a slide that pushed the rupee down more than 7 per cent in 2026 amidst heavy foreign capital outflows and elevated global oil prices.
When dealers arrived at their desks in Mumbai’s financial district, the currency had already signaled its reaction to a weekend of sweeping regulatory maneuvers published by the Reserve Bank of India in the early hours of Saturday, October 10. The central bank introduced four distinct measures in its latest effort to restore discipline to foreign exchange markets, addressing both speculative pressures and the immense dollar demand driven by energy imports.
The package follows months of relentless downward pressure. Since the beginning of 2026, foreign investors have pulled nearly $30 billion out of Indian equities, while official foreign exchange reserves dropped from a peak of $785 billion in early September down to $734 billion by October 2.
Targeting State Refiners and Forex Derivatives
At the center of the Reserve Bank of India’s intervention is a dedicated dollar-supply window established for three major state-run oil marketing companies: Indian Oil Corporation, Bharat Petroleum Corporation, and Hindustan Petroleum Corporation. By supplying greenbacks directly to these refiners, the central bank has removed a daily requirement of roughly $10 billion to $12 billion that previously competed in the open spot market.
🚨 Indian foreign reserves are about to go empty. India has already burned half of its fx capital to defend the rupee.And despite spending billions, the rupee is still trading near ₹97 against the U.S. dollar.According to estimates from bankers, the RBI has used around… pic.twitter.com/4wqaRMDKkR
— https://x.com/macropaperr/status/2111036749736743301
Alongside the direct oil window, the regulator tightened rules governing currency derivatives to curb speculative short-selling. Transactions without proof of underlying commercial exposure saw their allowable limits slashed by 95 per cent, dropping from $100 million down to $5 million. Lenders were also instructed to maintain a 20 per cent cash reserve requirement for currency contracts exceeding $2 million.
Over the past few months, we have observed a very high proportion of trades being cancelled and rebooked on the same day…The high proportion of same-day cancellations and rebooking indicated a significant speculative element in the forex derivatives market. We have, therefore, taken these measures to curb such excessive speculation.
Governor Sanjay Malhotra, via Deccan Chronicle
Market Rebound and Cost of Defense
The weekend actions triggered an immediate reaction in the currency markets. The rupee rebounded sharply, strengthening nearly 177 paise against the US dollar across two consecutive sessions from a Friday close of 96.73. Market observers noted that the timing of the intervention signaled an implicit tolerance threshold around the 97-per-dollar mark that the central bank intended to defend.
Yet analysts emphasize that defending specific exchange rates carries a heavy fiscal and structural toll. Brokerage reports estimate that the central bank has spent between $75 billion and $80 billion defending the currency from resources mobilized earlier in the year through special diaspora deposit programs and currency swaps.
External Headwinds and Long-Term Vulnerabilities
Despite the temporary reprieve, financial strategists caution that administrative curbs cannot fully eliminate macroeconomic pressures. India remains heavily reliant on energy imports, importing more than 85 per cent of its crude oil needs. Compounding the pressure, a February trade deal with Washington reduced American tariffs on Indian goods from 50 per cent to 18 per cent, but came with a condition to wind down purchases of discounted Russian crude, leaving the nation exposed to Middle Eastern pricing.
Furthermore, narrowing yield differentials between Indian and American policy rates have diminished the appeal of the rupee as a carry trade. While the central bank raised its repo rate by 25 basis points to 5.50 per cent on October 7, the gap with United States benchmark rates remains compressed compared to historical norms.
Our view is that, unless oil prices collapse, USD-INR faces upward pressure over time due to India’s wider current account deficit, inflation differential, lack of catalyst for portfolio inflows, and the RBI’s short FX forward position.
Joey Chew, head of Asia FX research at HSBC, via Business Recorder
Financial institutions project that currency pressures will persist into the coming year. Forecasts from economic strategists point toward the currency testing 97 to 98 per dollar by mid-2027, with some warning that a move toward the 100-per-dollar milestone cannot be ruled out if crude prices escalate further or foreign portfolio outflows resume.
