
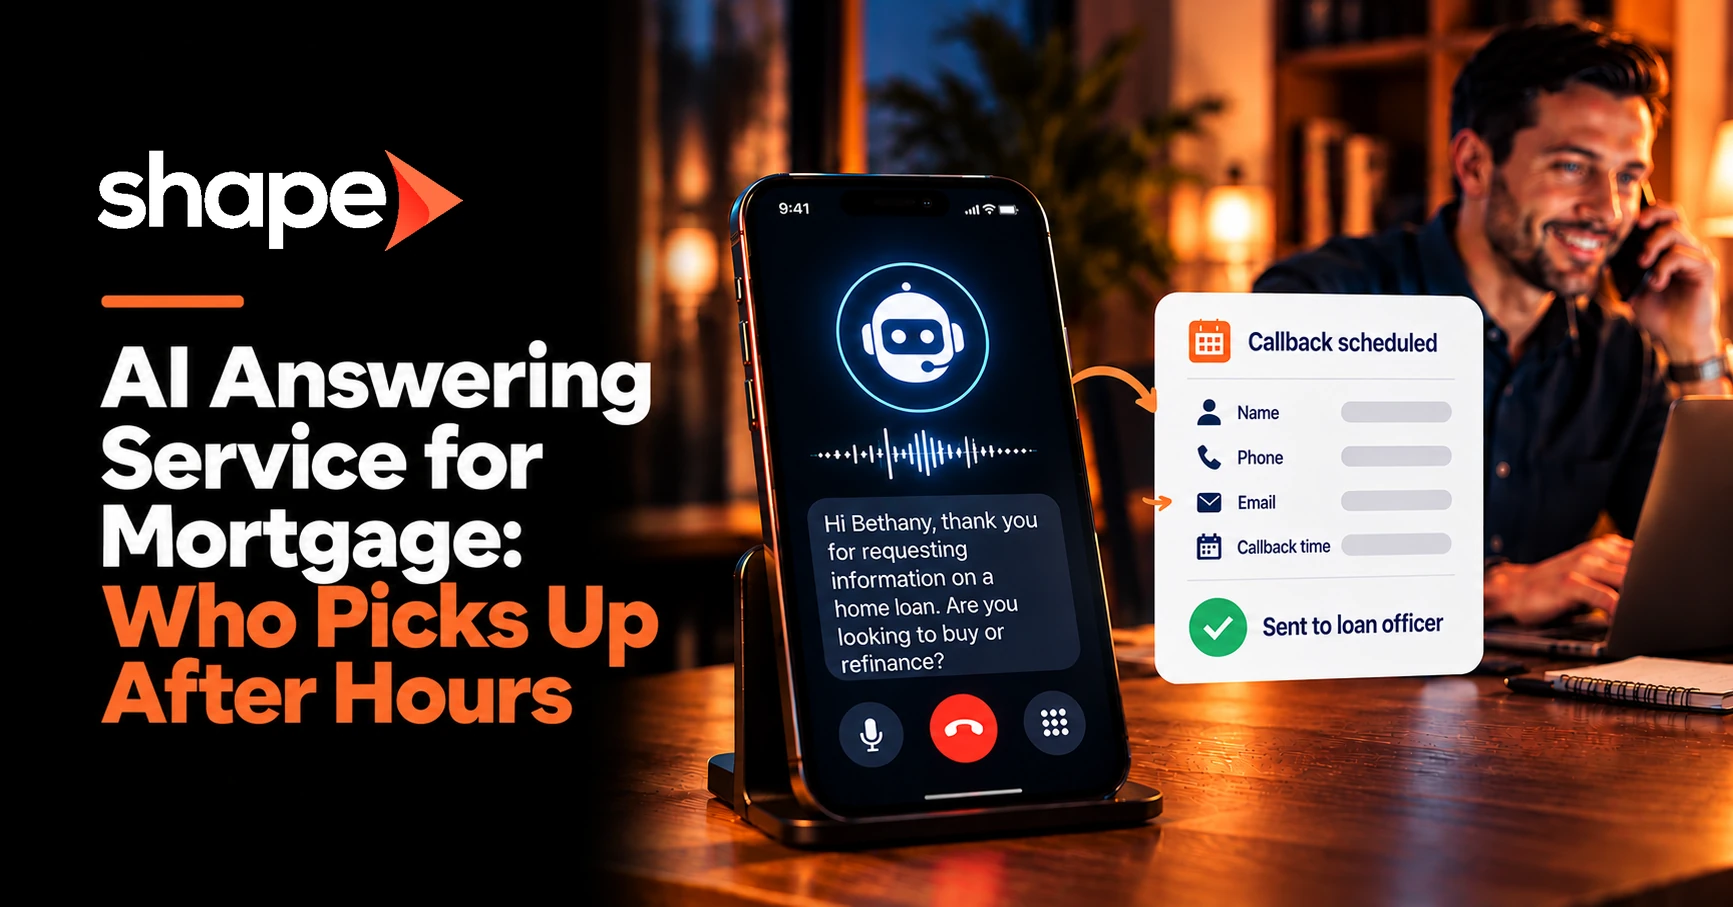
Shape’s AI answering service for mortgage lenders tackles after-hours lead capture by collecting caller details and booking callbacks. Under strict regulatory frameworks, the tool deliberately avoids quoting rates or taking applications, bridging the gap between missed inbound volume and licensed loan officers.
The Bottom Line
Strict Role Boundaries: The AI agent gathers four core items—purpose, name, phone number, and email—while strictly avoiding Regulation H triggers like loan term negotiations.
Native CRM Integration: Unlike standalone virtual receptionists, native agents log data directly onto borrower records and assign calendar callbacks without manual routing.
FCC and TCPA Compliance: Federal rules classify AI voices as artificial, meaning prior borrower consent obtained during the initial call must be verified against state-level calling restrictions.
Handling Inbound Mortgage Volume Without Crossing Regulation H
Missed mortgage calls represent direct revenue handed to competing lenders. Shape addresses this leak by deploying an artificial intelligence agent designed to keep the interaction strictly administrative. When floor staff cannot pick up, the system collects the borrower’s name, telephone number, email address, and the basic purpose of the conversation. It then schedules a callback time chosen directly by the borrower.
The system deliberately stops short of loan origination tasks. Under Regulation H, taking an application, offering loan terms, or negotiating rates requires a licensed mortgage loan originator. Shape’s software avoids these triggers. When callers press for rate quotes, the agent informs them that the loan officer covers it on the callback. Software design decisions regarding these boundaries ultimately rest with internal legal counsel.
Executing Callbacks and Managing Regulatory Compliance
An answering service only resolves half the operational friction; the callback completes the workflow. At the designated hour, the agent calls the borrower back. It confirms the time still works, then connects the borrower to the loan officer. This handoff ensures the borrower speaks with a professional who already understands the intent behind the inquiry.
However, this follow-up introduces regulatory scrutiny under the Telephone Consumer Protection Act. In 2024 the FCC ruled that AI-generated voices are “artificial” under the TCPA. Calls using an artificial voice need the consumer’s prior express consent. While the borrower selects a callback time during the initial interaction, teams must verify whether that selection satisfies consent requirements for an AI-voiced return call across different state jurisdictions.
Deploying Native CRM Agents Over Standalone Receptionists
Operational efficiency depends heavily on system architecture. Many third-party products operate as standalone receptionists, generating transcripts or webhooks that require manual data entry into existing platforms. In contrast, a native agent functions directly inside the CRM.
Details gathered by the native agent automatically populate the borrower’s file. The callback schedules itself cleanly on the assigned loan officer’s calendar, and call transfers utilize existing routing rules. This architecture eliminates duplicate data entry and prevents lead leakage between disparate software tools.
| Metric | Operational Focus | Performance Objective |
|---|---|---|
| Answer Rate | Inbound coverage | Maximize share of calls reaching a person or agent. |
| Callback Completion Rate | Follow-up execution | Track borrower engagement at the agreed time. |
| Connect Rate | Handoffs to staff | Measure completed callbacks successfully routed to loan officers. |
| Funded Rate | Revenue generation | Compare closed loans from agent-answered calls against live answers. |
Tracking Four Core Metrics to Measure AI Receptionist ROI
Evaluating automated phone coverage requires analyzing four specific performance metrics across both business hours and after-hours windows. Teams must monitor the answer rate, callback completion rate, connect rate, and funded rate. Comparing funded loans originating from agent-answered interactions against those from live answers reveals the true financial value of the deployment.
If automated-answer loans fund far below the rate of live answers, lenders typically examine callback timing rather than discarding the technology entirely. Where phone callbacks fail to connect, secondary channels like AI SMS for mortgage lead qualification can step in to maintain lead qualification efforts.
