
As consumer financing expands through technological innovation, banking leaders and experts are calling for consumer protection, responsibility, and higher standards of risk management. Speaking on the integration of financial technology and consumer protection, Dr. Dao Minh Tu, Vice President and General Secretary of the Vietnam Banks Association (VNBA), noted that technological innovation must go hand in hand with consumer protection and trust building.
Balancing Fintech Speed With Regulatory Accountability
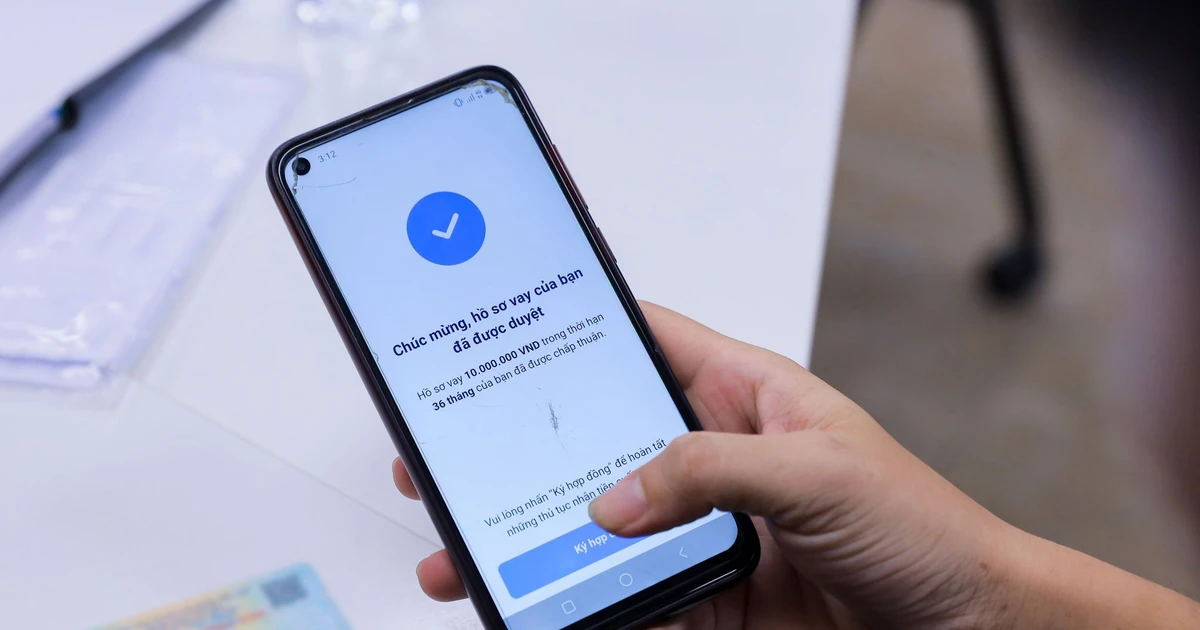
Rapid technological adoption allows financial institutions to slash processing times, broaden customer acquisition, and tailor products to individual needs. With simple tools like a chip-enabled ID card, customers can secure credit approvals through platforms such as Mcredit. However, as Tran Anh Quy, Deputy Director of the Credit Department at the State Bank of Vietnam (SBV), pointed out, this speed brings heightened demands for the quality of assessment, risk management, and accountability for data- and automation-supported credit decisions.
There are currently 16 consumer finance companies licensed by the SBV, of which 13 belong to the VNBA’s Consumer Finance Club. Consumers frequently mistake these regulated entities for credit apps or companies that fall under the Enterprise Law but do not possess an SBV license. To combat fraud and clarify market boundaries, Le Que Huong, Senior Director Digital and Brand at Shinhan Finance, proposed implementing a digital “anti-counterfeiting” seal for approved financial applications.
Reaching Unbanked Borrowers Through Digital Ecosystems
The push for digital transformation extends far beyond traditional banking halls, targeting underserved demographics who lack established credit histories. Le Xuan Dong, Managing Director for Market Research and Consulting at FiinGroup Vietnam, observed that a significant segment of the population remains excluded from formal financial systems. This includes Generation Z workers entering the workforce, low-income earners, and individuals with no credit history at the Vietnam National Credit Information Center (CIC) or the Vietnam Credit Information Corporation (PCB).
Because these consumers handle transactions primarily in cash without a digital footprint, traditional lending products frequently fail to meet their needs. Younger borrowers often require micro-scale, short-term payment solutions ranging from several hundred thousand to millions of dong over a period of days or weeks. Ho Minh Tam, General Director of VietCredit, explained that his firm underwent a comprehensive digital transformation following the COVID-19 pandemic to deliver products directly through integrated financial platforms and digital ecosystems, shifting away from branch-dependent models.
| Institution / Entity | Regulatory Status | Market Role |
|---|---|---|
| State Bank of Vietnam (SBV) | Regulator | Licenses financial companies; a separate chapter in the Law on Credit Institutions is dedicated to the financial company model. |
| Vietnam Banks Association (VNBA) | Industry Association | Houses the Consumer Finance Club. |
| Licensed Consumer Finance Firms | SBV-Regulated (16 total, 13 in VNBA Club) | Provides digital credit and micro-financing solutions to underserved segments. |
Establishing clear digital markers will allow users to confirm the legitimacy of a lending application within seconds, separating regulated financial institutions from unauthorized operators.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
