
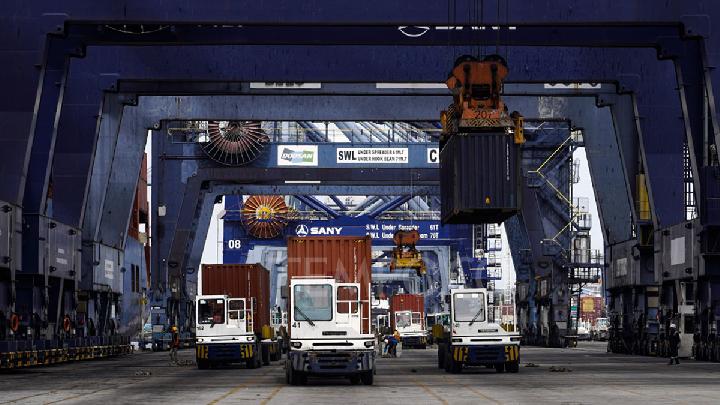
Global trade is enduring its most unpredictable postwar era as supply chains absorb simultaneous shocks from COVID-19 factory shutdowns, the wars in Ukraine and the Middle East, and sweeping U.S. tariffs implemented under President Donald Trump. Despite World Trade Organization warnings of serious and sustained disruptions, goods trade volumes rose 4.6% last year, heavily buoyed by demand for artificial intelligence hardware.
The Resilient Engine of AI Goods and Services
Even as geopolitical conflicts choke traditional energy corridors, global commerce has demonstrated surprising staying power. According to the World Trade Organization’s annual report published last week, global goods trade volumes grew by 4.6% over the previous year, while services trade climbed 5.3%. China maintained its position as the world’s largest goods exporter, with the United States retaining the top spot for imports, and the European Union placing second in both categories.
Here is why that matters: this overall growth largely masks underlying vulnerabilities. Robert Staiger, chief economist at the World Trade Organization, noted that strong artificial intelligence exports may be masking a broader drop in world trade that might otherwise be occurring. Asian economies dominated the AI goods trade, while regions like Africa, Latin America, the Middle East, and much of Europe showed minimal participation. AI-related technology accounted for approximately one-sixth of all goods trade but drove nearly half of total global trade growth.
Washington Shifts Strategy and Squeezes Trade Routes
Since returning to office last year, President Donald Trump has continued to pivot away from multilateral Geneva rules, instituting country-specific duties that break the World Trade Organization’s equal-treatment principle while negotiating individual exemptions and reciprocal tariffs. Globally, about 72% of goods are still traded on core agency terms, down from roughly 80% in 2022. But on a macro horizon, globalization has clearly stalled, with world trade growing only in tandem with the global economy since roughly 2015.
The friction is reshaping sourcing patterns entirely. U.S. imports from China fell by around 28% last year, according to data from the Peterson Institute for International Economics. To compensate, American firms rerouted supply chains, boosting imports from the rest of the world by nearly a tenth, with heavy increases coming from Vietnam, Taiwan, and Mexico.
Shifting Energy Flows Across Europe and the Middle East
The geopolitical landscape has forced dramatic structural changes in energy markets. Following Russia’s full-scale invasion of Ukraine in February 2022, the European Union slashed its reliance on Russian pipeline gas from 37% in late 2021 down to approximately 10%, according to Eurostat. European oil and coal imports from Russia are now negligible, replaced largely by liquefied natural gas from the United States, Norway, Australia, and Kazakhstan. Meanwhile, Moscow redirected its energy exports to new buyers in China and India at steep discounts to global benchmarks.
Camille Reverdy, an affiliate fellow at the Brussels-based think tank Bruegel, expressed skepticism that the European Union will return to Russian energy even after hostilities cease, stating that if alternative sources prove reliable, she does not see energy trade returning to past norms. Compounding these fractures, the outbreak of the war involving Iran in late February led to the effective shutdown of the Strait of Hormuz, one of the world’s most vital energy transit chokepoints.
| Metric / Sector | Previous Baseline | Recent Shift / Current Status |
|---|---|---|
| Global Goods Trade Volume | Stalled relative to GDP post-2015 | Rose 4.6% last year, driven heavily by AI infrastructure demand |
| EU Reliance on Russian Pipeline Gas | 37% in late 2021 | Dropped to approximately 10%, replaced by LNG from U.S., Norway, Australia, and Kazakhstan |
| U.S. Imports from China | Pre-tariff baseline | Fell by around 28% last year, with increases redirected to Vietnam, Taiwan, and Mexico |
| WTO Core Terms Trade Share | Roughly 80% in 2022 | Declined to about 72% amid bilateral U.S. tariffs and exemptions |
Navigating an Uncertain Economic Horizon
To offset the sudden closure of the Strait of Hormuz, Saudi Arabia and the United Arab Emirates rerouted portions of their missing oil through alternative pipelines. Simultaneously, the International Energy Agency confirmed that increased production from the United States, Kazakhstan, Brazil, and Venezuela—alongside the release of roughly 300 million barrels from strategic reserves reported by Reuters in August—helped backfill global markets.
Yet, energy prices remain elevated, with Brent crude trading above $100 for much of the conflict, leaving analysts warning of dangerously tight supplies as demand fluctuates. As Thomas Sampson, an associate professor at the London School of Economics, observed to DW, the world is certainly not becoming more globalized, leaving an open question as to whether current friction represents true deglobalization or merely a permanent realignment of international trade partners.
Related reading
- Sydney Kings vs Brisbane Bullets: NBL27 Preview, Rosters & How to Watch
- Former Romanian Presidential Candidate Călin Georgescu Arrested for Fraud
- Trump and AI executives sign agreement on safety of advanced models (world-today-journal.com)
- US-Canada Trade War: Impact of Booze Bans on Canadian Producers (archyworldys.com)
