
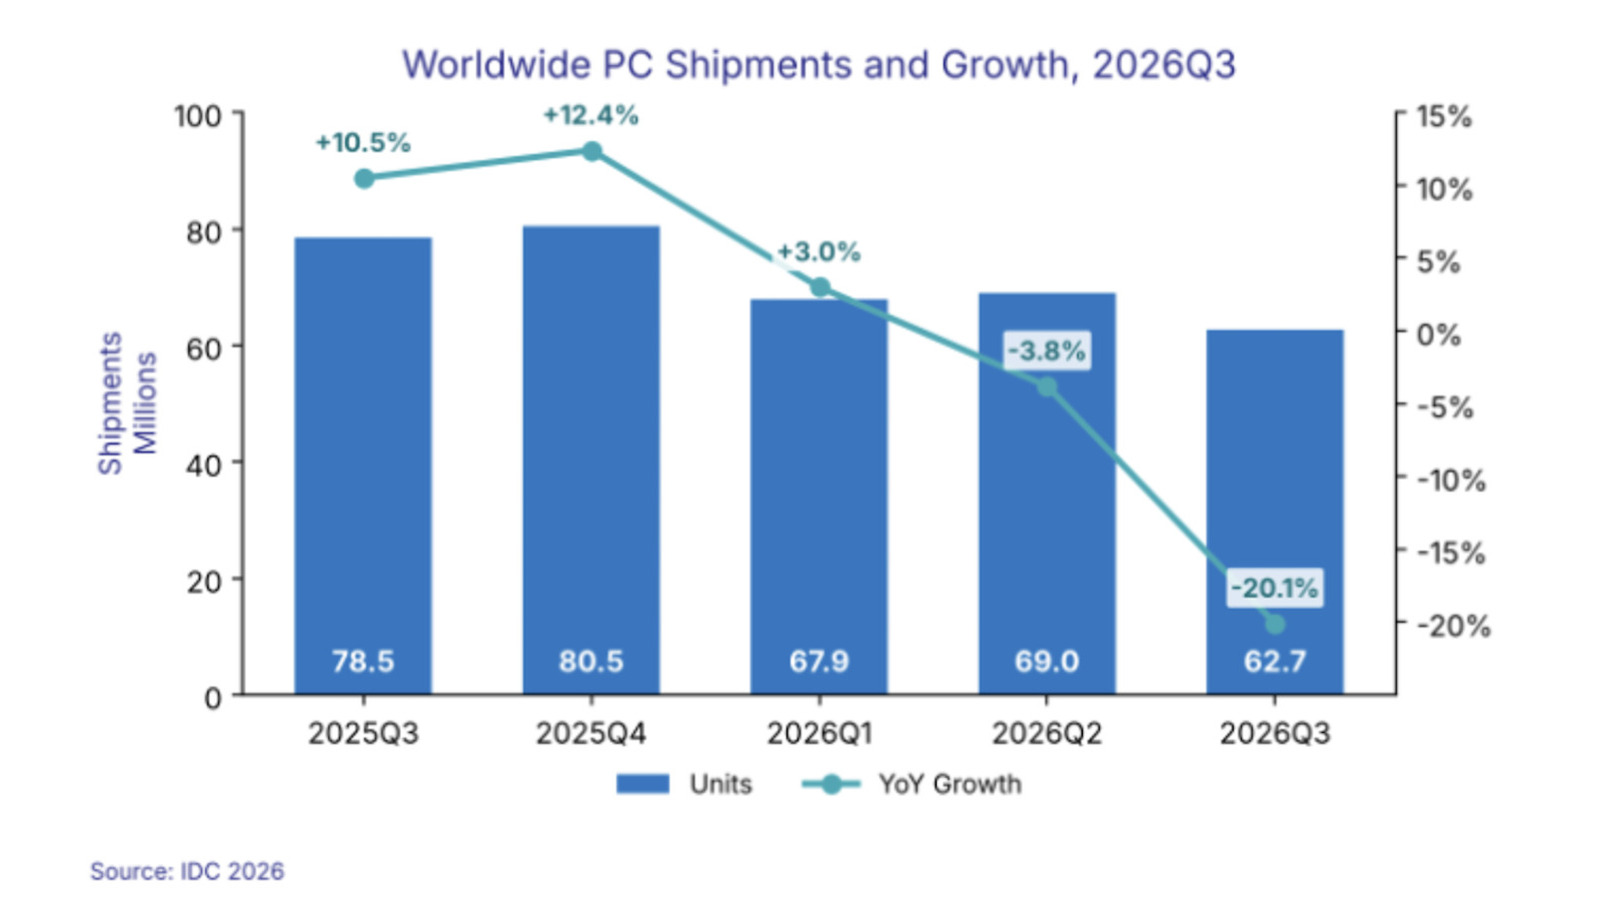
Global personal computer shipments dropped 20.1 percent year over year during the third quarter of 2026, driven by soaring component costs and inventory corrections following an early buying rush.
The personal computer industry just recorded its sharpest downturn since Q1 2023, as preliminary market figures reveal a steep contraction across desktop and laptop sales.
Third-Quarter Shipment Volumes and Market Contractions
Global shipments for laptops, desktops, and workstations fell to 58.1 million units, representing a 21.2 percent decline compared to the same period in the previous year, according to data from Omdia. The International Data Corporation reported a slightly higher worldwide total of 62.7 million units, marking a 20.1 percent drop year over year from the 78.5 million units shipped in Q3 2025.
The contraction ran counter to typical seasonal trends. While the third quarter traditionally outperforms the second quarter due to back-to-school purchasing, IDC estimated that shipments fell 9.1 percent from the 68.2 million units recorded in Q2 2026.
Desktop computers experienced the steepest slide among form factors. Desktop PC shipments—including workstations—decreased by 23.5 percent down to 11.7 million units. Laptop shipments, which include mobile workstations, dropped 20.6 percent to 46.4 million units.
Component Costs and AI-Driven Memory Shortages
Analysts attribute the supply crunch primarily to intense competition for computer memory. The rapid expansion of artificial intelligence data centers has driven up demand for DRAM and NAND flash storage, absorbing supplies that previously supported consumer hardware.
Omdia estimates that memory components now account for nearly 40 percent of a typical PC’s bill of materials, climbing from roughly 15 percent previously following price surges of more than four times. Manufacturers have also faced ongoing shortages affecting processors, graphics cards, and other integrated circuits.
Anticipating these rising expenses, many vendors and sales channels accelerated purchases earlier in the year. Industry buyers rushed to secure inventory before impending price hikes took full effect, artificially inflating figures during the first half of 2026.
“What we’re seeing is the result of the strong first half pull-in.”
Vendor Rankings and Market Share Shifts
Major hardware brands experienced widespread shipment declines, though performance varied by manufacturer. Lenovo maintained its position as the world’s largest PC vendor despite shipping 14.9 million units, reflecting a 22.6 percent year-over-year decrease.
HP absorbed the steepest drop among major manufacturers, with shipments plunging 30.9 percent to 10.3 million units. Dell recorded a 25 percent reduction down to 7.6 million units.
Apple weathered the contraction better than most competitors. Apple shipped an estimated 5.9 million Macs during the third quarter—down 11.3 percent from 6.7 million a year earlier—while expanding its market share from 8.5 percent to 9.5 percent and retaining fourth place in IDC vendor rankings. ASUS recorded an 8.6 percent decrease with 5.5 million shipments, making it the only other top-five vendor to contract slower than the wider market.
Inventory Pressures and Near-Term Outlook
Sales channels are now working through excess stock while managing suppressed consumer demand. High retail prices have discouraged many potential buyers from upgrading existing hardware.
Omdia projects that global shipments will decline another 24 percent year over year in the fourth quarter of 2026, accompanied by an additional 7 percent drop across 2027.
