
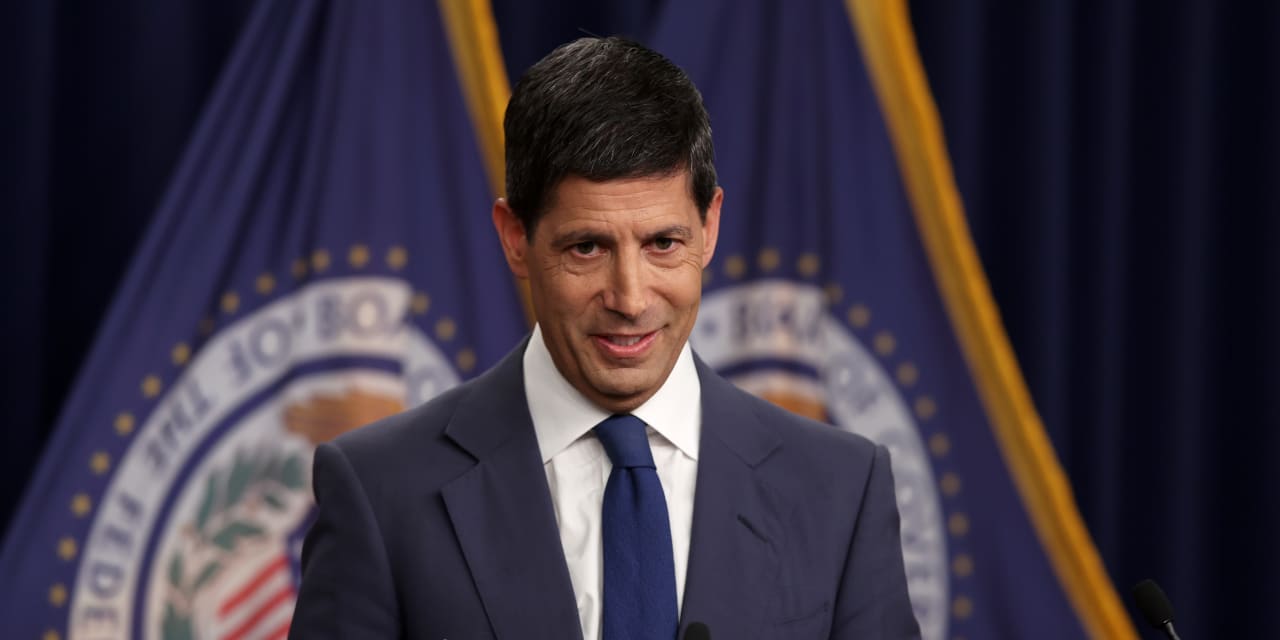
Federal Reserve Chair nominee Kevin Warsh has repeatedly committed to anchoring U.S. inflation at the 2.0% target, yet structural fiscal deficits and a rapidly expanding national debt profile make that monetary objective mathematically improbable without aggressive policy intervention or persistent currency devaluation.
The Bottom Line
- The Core Conflict: Maintaining a 2.0% inflation target requires restrictive monetary policy, but servicing high federal borrowing costs creates persistent expansionary pressure.
- Macroeconomic Reality: According to recent fiscal data, structural deficits force the Treasury to continuously issue high volumes of debt, complicating the Federal Reserve’s balance sheet normalization.
- Market Impact: Fixed-income investors face prolonged yield curve volatility as bond supply outpaces organic institutional demand.
The Arithmetic Trap Facing Modern Central Banking
Monetary policy does not operate in a fiscal vacuum. When central bankers commit to a 2.0% inflation ceiling, they assume a cooperative fiscal framework where government spending aligns with productive economic output. But the current balance sheet of the United States tells a different story.
Here is the math: as federal debt accelerates toward historic thresholds relative to Gross Domestic Product, the cost of servicing that debt consumes a larger share of federal outlays. To prevent severe liquidity contractions, the financial system often relies on indirect liquidity injections. Consequently, these structural dynamics work against the Federal Reserve’s stated objective of price stability.
Financial analysts monitoring forward yield curves note that the market has begun pricing in a higher term premium. According to data from the Federal Reserve Bank of St. Louis (FRED), long-term Treasury yields continue to reflect persistent inflationary expectations that consistently outpace the central bank’s ideal 2.0% benchmark.
Examining the Debt-to-GDP Feedback Loop
When debt expands faster than organic GDP growth, the economy enters a feedback loop. Traditional economic theory suggests that raising interest rates cools demand and tames price growth. However, in an over-leveraged fiscal environment, higher rates increase the government’s interest payment obligations, effectively pumping more cash into the broader economy.
This dynamic neutralizes part of the tightening effect that central bankers attempt to achieve. Major institutional desks have highlighted this friction. As noted by analysts at Goldman Sachs Group Inc. (NYSE: GS) in recent macroeconomic notes, structural fiscal imbalances remain the primary risk factor for long-term bond vigilantes.
| Economic Metric | Current Level / Status | Federal Reserve Target |
|---|---|---|
| Headline Inflation Rate | Tracking above 2.5% YoY | 2.0% Fixed Anchor |
| Federal Debt-to-GDP | Exceeding 120% | Historically Sustainable (<90%) |
| 10-Year Treasury Yield | Hovering near 4.2% | Market-Determined |
Market Implications for Equities and Fixed Income
For institutional asset managers, the inability to reliably anchor inflation at 2.0% shifts portfolio construction strategies. Equities with strong pricing power and robust balance sheets—such as those found within the S&P 500 (INDEXSP: .INX)—typically outperform during periods of persistent structural inflation. Conversely, capital-intensive sectors face margin compression as debt refinancing costs rise.
Furthermore, currency markets are adjusting to the reality of U.S. fiscal dominance. The U.S. Dollar Index (DXY) faces cross-currents as global central banks evaluate the long-term credibility of American debt instruments. If the market loses confidence in the Federal Reserve’s ability to decouple monetary policy from fiscal pressures, capital may rotate rapidly toward alternative hard assets.
The Road Ahead for Monetary Credibility
Achieving a durable 2.0% inflation rate requires more than verbal commitments from leadership; it demands fiscal discipline that currently remains absent from legislative projections. Until federal outlays align with structural revenues, the central bank’s inflation mandate will remain under constant pressure.
Investors must prepare for a macroeconomic environment where nominal growth remains elevated, real returns are compressed, and volatility is the baseline condition for both bond and equity portfolios.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
