
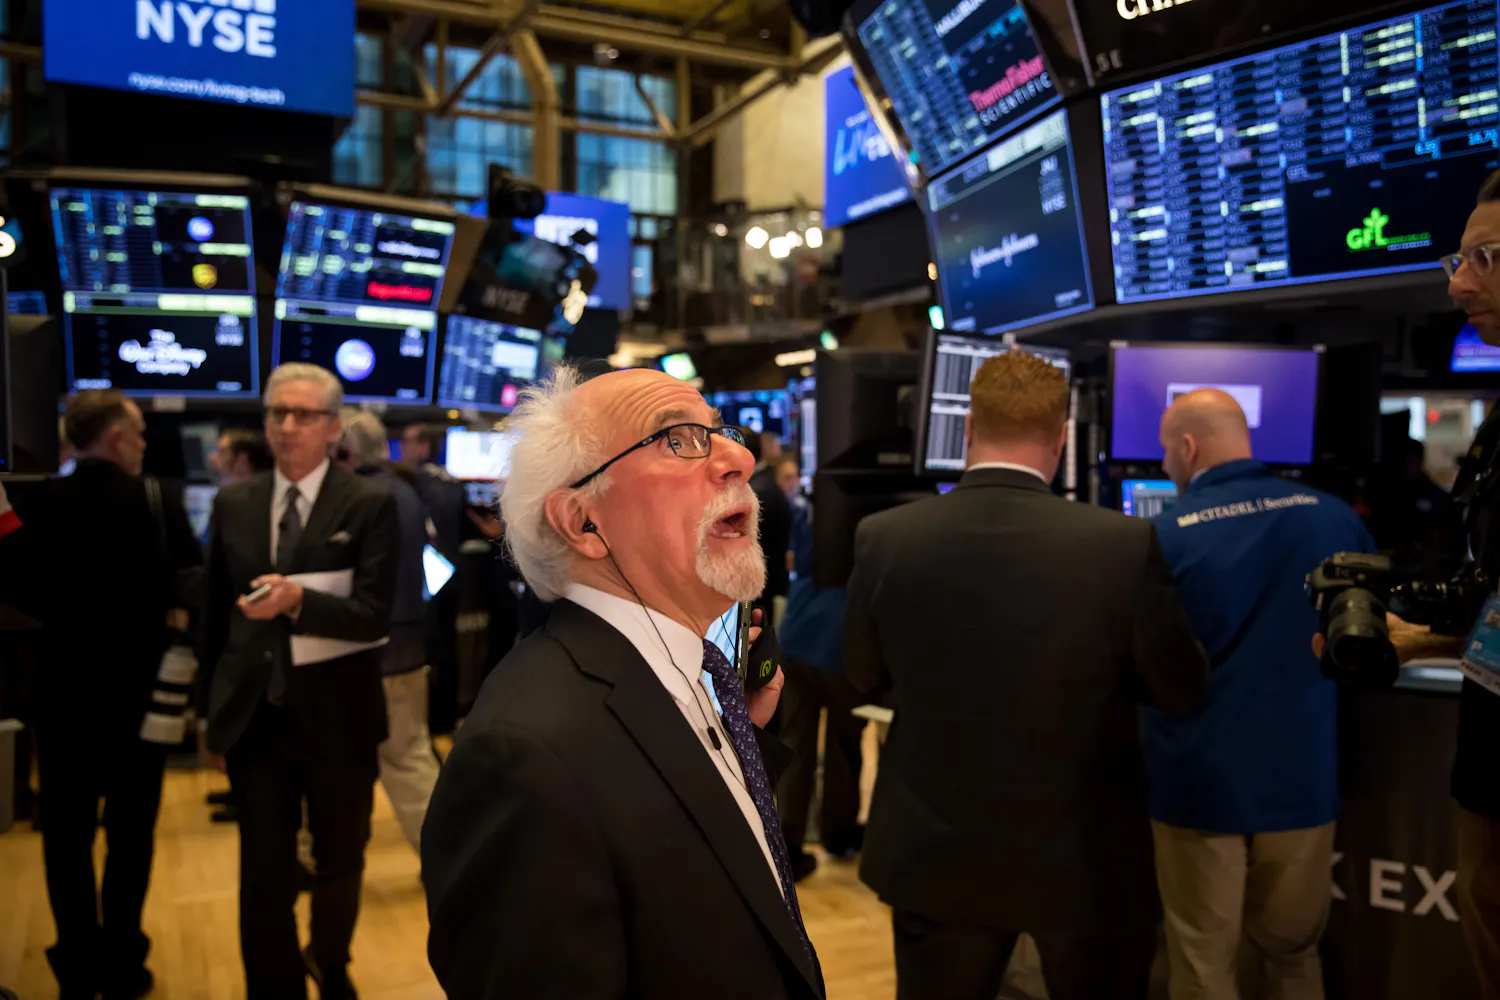
The global bond market has kicked off the fourth quarter with sharp volatility as long-term government debt yields climb across Japan, Australia, the Netherlands, France, and Germany. The 10-year US Treasury yield recently reached its highest level since 2002 at 5.34%, driven by surging mortgage rates and the effect of rising interest rates on those mortgages.
The Bottom Line
- Yield Surge: The 10-year US Treasury yield hit 5.34% in early October, marking its largest quarterly jump this century with an increase of nearly 90 basis points (0.9 percentage points).
- Equity Premium Erasure: Rising bond yields have pushed the equity risk premium on Wall Street into negative territory, as the S&P 500 earnings yield sits below alternative fixed-income returns.
- Sovereign Debt Strain: Prime Minister Sébastien Lecornu presented France’s 2027 recovery budget aiming for €54 billion in cuts, as French national debt climbs toward 121.7% of GDP—the highest level since 1946.
Global Sovereign Yields Hit Multi-Decade Highs
Global bond markets faced renewed pressure entering the fourth quarter as long-term government debt yields climbed worldwide. Visser, speaking via BNR, noted that after a brief stabilization earlier in the week, upward momentum resumed rapidly across multiple sovereign debt markets.
The 10-year U.S. Treasury yield touched 5.34%, levels not recorded since 2002. Similar multi-decade highs appeared across Europe and Asia, affecting long-term debt in Japan, Australia, the Netherlands, France, and Germany. British 30-year borrowing costs also breached the 6% threshold for the first time since 1998.
Mortgage Linkages Trigger Self-Reinforcing Yield Spirals
The primary driver behind the expanding sovereign yields involves the direct transmission mechanism between benchmark bonds and retail borrowing costs. As BNR reported, rising bond yields feed directly into mortgage rates across the United States and Europe.
Higher mortgage rates force consumers to extend their repayment horizons, magnifying portfolio risk for institutional investors. To mitigate this exposure, insurers and pension funds divest portions of their government bond holdings, inducing further sell-offs and accelerating an upward loop in market interest rates.
France Confronts Record Debt Ratios in 2027 Budget
Sovereign fiscal health remains a core catalyst for market nervousness. In France, Prime Minister Sébastien Lecornu introduced the 2027 recovery budget, targeting €54 billion in total expenditure reductions. Lecornu sounded alarms over accelerating debt-servicing costs as national liabilities approach 3.6 trillion euros.
French public debt is projected to expand to 121.7% of gross domestic product in 2027, surpassing the current 119% ratio—which already marks the largest burden carried by the French state since 1946. While the fiscal tightening is aggressive, Visser observed that markets ultimately scrutinize political credibility rather than raw fiscal targets alone.
Comparing Global Bond Yields and Equity Valuations
With sovereign yields offering returns above 5%, institutional allocators are re-evaluating traditional equity allocations. The changing yield environment has compressed the equity risk premium.

| Region / Index | 10-Year Bond Yield | Forward P/E Ratio | Earnings Yield |
|---|---|---|---|
| United States (S&P 500) | 5.21% – 5.34% | ~21.5x | 4.6% |
| United Kingdom (FTSE 100) | Higher | ~13.0x | Higher |
| Netherlands (AEX) | Lower | Lower | ~6.7% |
On Wall Street, the S&P 500 trades at roughly 21.5 times expected forward earnings, producing an inverse earnings yield of 4.6%. With 10-year Treasuries yielding above 5.2%, the traditional cushion held by equities has inverted into a negative premium.
Private Investors and AI Capital Expenditures Drive Supply
Structural changes in market participation are reshaping how sovereign debt is absorbed. Data from Janus Henderson portfolio manager James Briggs indicates that official buyers like the Federal Reserve have receded, elevating the ownership share of domestic private investors from 30% to 50%.
Simultaneously, massive capital expenditure cycles—particularly heavy corporate debt issuance to finance artificial intelligence infrastructure—continue to test market capacity. Grote economieën geven inmiddels meer uit aan rentebetalingen dan de wereld investeert in AI, defensie of schone energie.
Keep reading
- Ghent startup Falcon launches AI contract service for monthly fee
- Latvia credit expansion grew in August per European Central Bank data
- UK mortgage market reshaped by property taxes and rate volatility, DBRS says (newsdirectory3.com)
- Zimbabwe To Host COMESA Business Forum Targeting Trillion Dollar Market (time.news)
