

Stock futures showed little movement early Monday as investors weighed a multi-decade high in Treasury yields against upcoming updates from the Federal Reserve. Futures tied to the Dow Jones Industrial Average added 53 points, or 0.1%, while S&P 500 futures rose 0.1% and Nasdaq-100 futures ticked up 0.2%.
The Bottom Line
- Data Calendar: Investors are shifting focus toward upcoming economic releases, including the ISM services activity report, September Fed meeting minutes, and the University of Michigan’s consumer sentiment reading.
- Earnings Horizon: The unofficial start of earnings season looms large, with major reports from corporations like JPMorgan scheduled for October 13.
Yield Pressures Counter Tech Momentum
The muted futures activity follows a strong Friday session on Wall Street where the blue-chip Dow added 250 points, or 0.5%, to close at 51,176.46. The broader S&P 500 climbed 0.7% to 7,722.72, and the tech-heavy Nasdaq Composite rallied 1.2% to 27,190.86 after hitting an intraday record.
Yet, the underlying macro environment remains tense. Surging bond yields continue to dominate investor calculations.
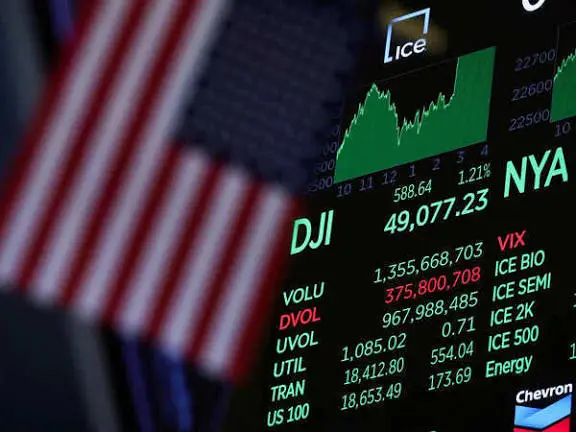
Olumide Adesina reported that the broader market recently wrapped up September with a minor monthly pullback, noting that the Dow spot index settled near 51,011 amid profit-taking and end-of-quarter rebalancing. Adesina observed that while select tech and consumer discretionary components—such as Salesforce, Apple, and Amazon—showed relative strength, industrial and retail giants like Walmart and 3M faced noticeable headwinds.
Asian Markets Rise as US Indices Close Higher
Overseas trading presented a stronger picture at the start of the week. In Asia, Japan’s Nikkei 225 added over 1.7%, while the broader Topix rose 0.79%. Australia’s benchmark S&P/ASX 200 gained 0.53%, while markets in mainland China and South Korea remained closed for holidays.
| Index / Asset | Recent Performance / Level | Key Driver |
|---|---|---|
| Dow Jones Industrial Average | Closed at 51,176.46 (+0.5% on Friday) | Blue-chip strength and end-of-week buying |
| S&P 500 | Closed at 7,722.72 (+0.7% on Friday) | Broad market lift led by tech sector gains |
| Nasdaq Composite | Closed at 27,190.86 (+1.2% on Friday) | Intraday record highs led by semiconductor momentum |
| U.S. 10-Year Treasury Yield | Highest level in more than two decades | Persistent inflation tracking and rate-path uncertainty |
With a relatively light economic calendar dominating the days ahead, market participants are looking toward upcoming corporate earnings and key central bank disclosures. Gary Schlossberg, global strategist for Wells Fargo Investment Institute, pointed out that investors are currently responding to the ebb and flow of geopolitical and market-specific developments matched against supportive economic reports ahead of the unofficial earnings season kickoff.
The domestic schedule features the Institute for Supply Management’s services activity report on Monday, followed by the release of the Federal Reserve’s September meeting minutes on Wednesday. The University of Michigan’s preliminary October consumer sentiment reading is slated for Friday.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
