
Financial regulators in South Korea are including loan maturity extensions in their official statistics for new real estate project financing, making total figures look higher than actual fresh market activity, fnnews.com reported.
The 23.5 Trillion Won Illusion
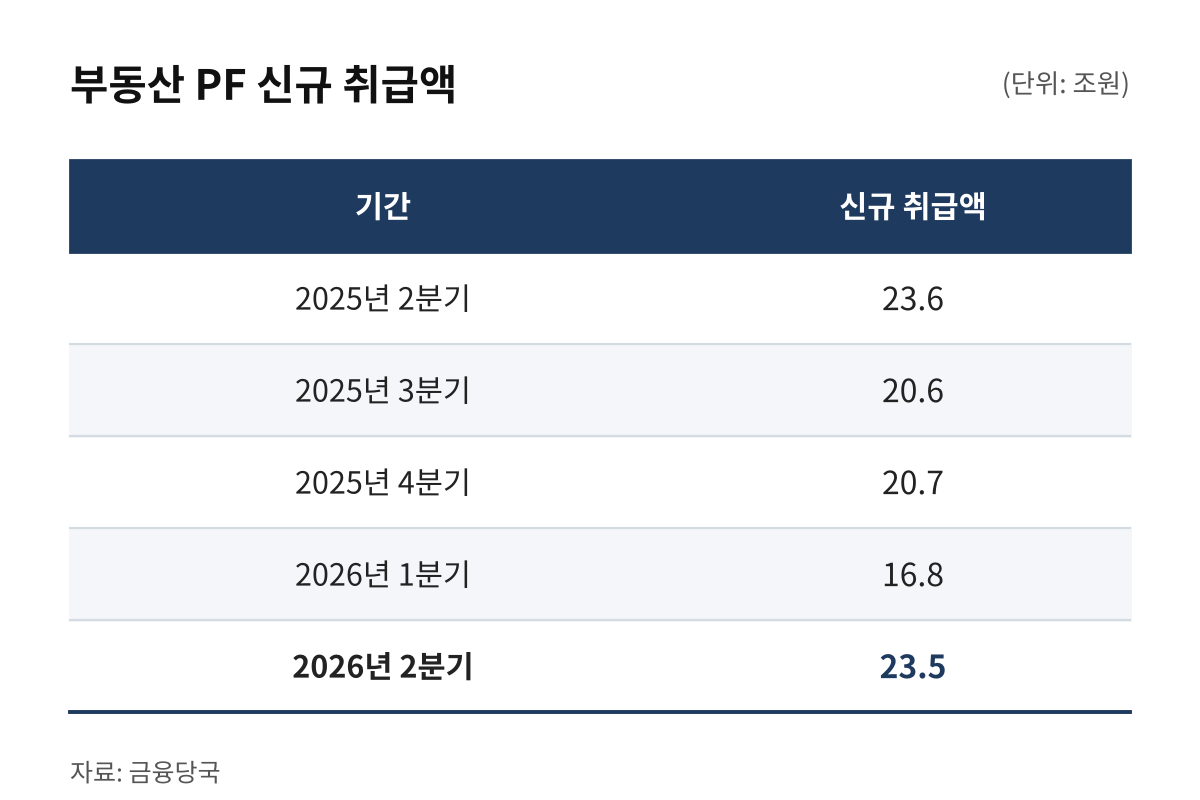
Data from the financial authorities show that second-quarter new real estate project financing acquisition volume reached 23.5 trillion won, climbing from 16.8 trillion won in the first quarter.
Since the second quarter of last year, quarterly figures have consistently stayed above 20 trillion won. But the balance sheet tells a different story. These official tallies count traditional loan maturity rollovers as new originations if the lending syndicate changes, masking a frozen primary market.
Decoding the Metric Distortion
Authorities treat any rollover involving a shifted syndicate as a fresh loan issuance, pushing Q2 acquisition volume to 23.5 trillion won.
Industry participants maintain that genuine fresh capital deployment is restricted to bridge loans and select high-grade residential developments, leaving the broader sector inactive.
Ignored Pleas From Developers
Developers have repeatedly petitioned regulators to separate pure originations from rollovers, though reporting methodologies remain unchanged. Industry stakeholders argue that counting loan extensions as fresh credit distorts reality.
One industry insider noted that only uncommitted bridge loans should count toward new volume, stating that routine maturity rollovers across existing obligations cannot be classified as newly originated debt. Developers have repeatedly requested a dedicated statistic tracking pure, uncommitted real estate project financing. Despite these appeals, regulators have not adjusted their reporting framework.
A Standstill in Property Lending
Meanwhile, the primary market remains largely inactive despite public guarantee programs designed to inject liquidity. While rollovers continue under stringent conditions, genuine new property lending is sparse.
High borrowing costs have brought new property development to a near standstill, limited almost exclusively to pre-sale purchase agreements and prime-location apartments. Major construction firms have largely pulled back from credit enhancements for project financing.
Blocked Avenues for Small Developments
For smaller developments, alternative avenues like land trusts managed by real estate trust companies remain blocked. The breakdown of the development and supply ecosystem continues to play out across the market.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial advice.
