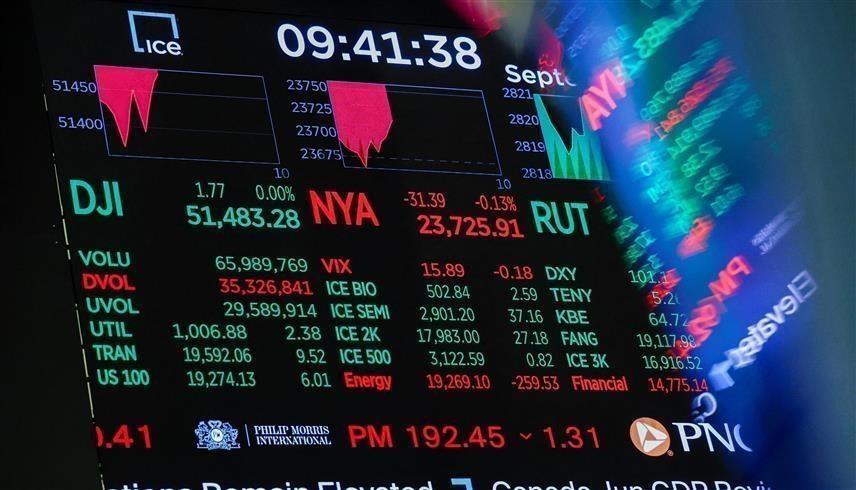
As markets approach a crucial Federal Reserve rate decision on October 23, 2026, Brent crude futures hover near $117 per barrel due to escalating Middle East supply risks. This energy surge triggered a broad retreat in U.S. equities and Treasury bonds, driving the S&P 500 (INDEXSP: .INX) lower and compressing bond yields as investors pivot toward defensive positioning.
The Market Reality at the Close of Q3
- Equities Retrench: The Dow Jones Industrial Average (INDEXDJX: .DJI) declined 1.2%, while the Nasdaq Composite (INDEXNASDAQ: .IXIC) absorbed steep tech-sector pressure following high-stakes corporate earnings.
- Crude Pressure: Brent crude trading near $117 per barrel directly exacerbates inflation concerns, complicating the upcoming monetary policy calculus for the central bank.
- Yield Dynamics: U.S. Treasuries surrendered portions of their prior-session gains as safe-haven demand fluctuated wildly between equities and fixed income.
- Geopolitical Risk: Ongoing regional conflicts in the Middle East continue to inject severe volatility into global energy supply chains and risk assets.
Crude Oil Surge Amplifies Inflationary Pressures Ahead of Fed Meeting
The macroeconomic backdrop heading into the Federal Reserve’s rate deliberations is defined by a renewed commodity shock. Escalating geopolitical tensions pushed Brent crude to $112–$114 per barrel, reviving fears of persistent, sticky inflation. Regional frictions involving Middle Eastern actors have driven crude to five-month highs, forcing fixed-income and equity investors to re-price terminal interest rate expectations.
Traders currently price in a 10% probability of a rate hike at the upcoming meeting, while CME FedWatch data indicates an approximate 90% probability of a rate adjustment by December. Tiffany Wilding of Pacific Investment Management observed that while inflation remains above target, it is not aggressively accelerating, which affords the Federal Reserve room to maintain a measured, data-dependent pace. However, the transmission of high energy costs into consumer prices threatens to upend this gradualist baseline.
AI Infrastructure Spending Pressures Tech Shares
The equity market sell-off extended far beyond commodity desks, centering heavily on high-valuation artificial intelligence beneficiaries. The Nasdaq Composite (INDEXNASDAQ: .IXIC) registered its largest daily loss since June, pressured by capital expenditure disclosures from mega-cap technology firms. Meta Platforms (NASDAQ: META) saw its shares drop 5.31% to $660.51, weighed down by rising debt insurance costs and substantial capital outlays dedicated to AI infrastructure scaling.
Similarly, Tesla (NASDAQ: TSLA) shares declined 2.62% to $376.34 despite posting unexpected positive free cash flow. Semiconductor names also absorbed heavy liquidations. Nvidia (NASDAQ: NVDA) fell 1.65% to $218.25, and Micron Technology (NASDAQ: MU) retreated 2.20% to $893.60, reflecting a broader investor reassessment of return on invested capital (ROIC) for hardware suppliers. Infrastructure lenders like CoreWeave fell roughly 10% during the peak of the tech rotation, illustrating the vulnerability of debt-financed data center operators.
| Company / Index | Ticker | Recent Price / Change | Key Driver |
|---|---|---|---|
| Meta Platforms | NASDAQ: META | -5.31% ($660.51) | AI capital expenditure and debt costs |
| Tesla | NASDAQ: TSLA | -2.62% ($376.34) | Positive cash flow offset by growth spending concerns |
| Nvidia | NASDAQ: NVDA | -1.65% ($218.25) | Semiconductor valuation compression |
| S&P 500 Index | INDEXSP: .INX | -1.19% (7,664.77) | Broad equity correction and energy drag |
Treasury Yields Stabilize as French Bond Stress Rises
As risk sentiment deteriorated, capital flows fragmented across asset classes. The yield on the 10-year U.S. Treasury note edged up to 4.9697%, stabilizing after a sharp flight-to-safety rally earlier in the week. Meanwhile, European sovereign debt experienced acute stress; the 10-year French government bond yield jumped to 5.1415%—its highest level since 2002—widening the bund spread to 174 basis points amid ongoing French political uncertainty and broader regional selling across the Stoxx Europe 600.
Michael Hartnett of Bank of America advised clients in a Friday note to maintain a tactical, risk-off posture through mid-November, citing lingering political headwinds from U.S. midterm elections and structural exhaustion in AI-themed equities. Conversely, institutional voices like Ulrike Hofmann-Burchard of UBS argued that robust corporate earnings profiles and steady underlying demand for enterprise technology will ultimately cushion the broader market against systemic declines.

Strategic Rebalancing as Market Breadth Narrowed
Underneath the headline index declines, market mechanics revealed a stark bifurcation. While the traditional S&P 500 (INDEXSP: .INX) dropped 1.21%, the equally weighted variant of the index gained 0.77%, demonstrating that capital rotated out of concentrated mega-cap technology and into defensive equities such as consumer staples. Companies like General Mills (NYSE: GIS) and Campbell Soup Company (NASDAQ: CPB) registered gains exceeding 8% during the session.
Brian Jacobsen of Annex Wealth Management emphasized that this divergence underscores the risk of portfolio concentration. The practical takeaway is not to abandon growth stocks, but to check whether one of the investment trends has quietly become dominant in the portfolio after a long period of gains,
Jacobsen noted. Rebalancing overextended positions into laggards remains the primary mechanism for institutional risk mitigation as the Federal Reserve prepares to deliver its definitive policy statement.