

Government land transaction permit regulations aimed at stabilizing the South Korean housing market have instead coincided with an 88-week upward trajectory in Seoul apartment prices and a severe tightening of rental inventories over the past year. Analysts point to structural supply contractions and shifting liquidity as core drivers behind the ongoing price escalation.
The Bottom Line
- Regulatory Fallout: The mandate requiring two years of actual residency for buyers within designated permit zones effectively eliminated gap investing, which in turn depressed traditional jeonse (long-term lease) supplies.
- Price Divergence: While high-end districts in Seoul showed temporary cooling, mid-to-lower tier neighborhoods and southern Gyeonggi province experienced sharp transaction surges and rising valuation indices.
- Policy Dilemma: Policymakers face mounting calls from industry experts to consider a phased exit strategy for specific core sectors, balancing structural supply deficits against persistent market liquidity.
One Year of Comprehensive Permit Rules and Stagnant Rental Inventories
Marking one year since the implementation of broad real estate tightening measures, data from the Korea Real Estate Board highlights the friction between state intervention and market mechanics. Under the policy framework introduced by the Ministry of Land, Infrastructure and Transport, authorities designated all of Seoul and 12 regions in Gyeonggi Province—including Seongnam, Gwacheon, and Hanam—as land transaction permit zones and regulated areas, adding further restrictions to existing speculative-overheated zones. By July, three additional districts such as Hwaseong’s Dongtan area were incorporated into the regulatory perimeter. The land transaction permit regulations remain valid through the end of the year, with the government slated to determine whether to extend them at year’s end.
The core mechanism of the land transaction permit system requires buyers of residential apartments to personally reside in the property for two years. According to reports from KBS News and MBC News, this legal mandate immediately outlawed gap investments—purchases utilizing tenant leases to finance acquisitions—thereby starving the rental market of new multi-unit supply. The Korea Real Estate Board’s jeonse supply-demand index climbed from 103.9 in October of last year to 122.4 by mid-October, illustrating the contraction in available lease properties. Seoul apartment jeonse listings fell 16.6% compared to a year prior, while the cumulative jeonse increase rate in Seoul reached 8.55% this year.
Diverging Regional Dynamics Across Seoul and Gyeonggi Province
Market reactions varied sharply across municipal boundaries. As covered by reports, prime districts historically leading market sentiment—specifically Gangnam (-0.35%), Seocho (-0.27%), and Song,pa (-0.21%)—recorded downward movements over a six-week stretch. However, Yongsan reversed its previous downward trend to register a 0.03% increase, signaling shifting momentum similar to historical pre-tax-deadline rebounds.
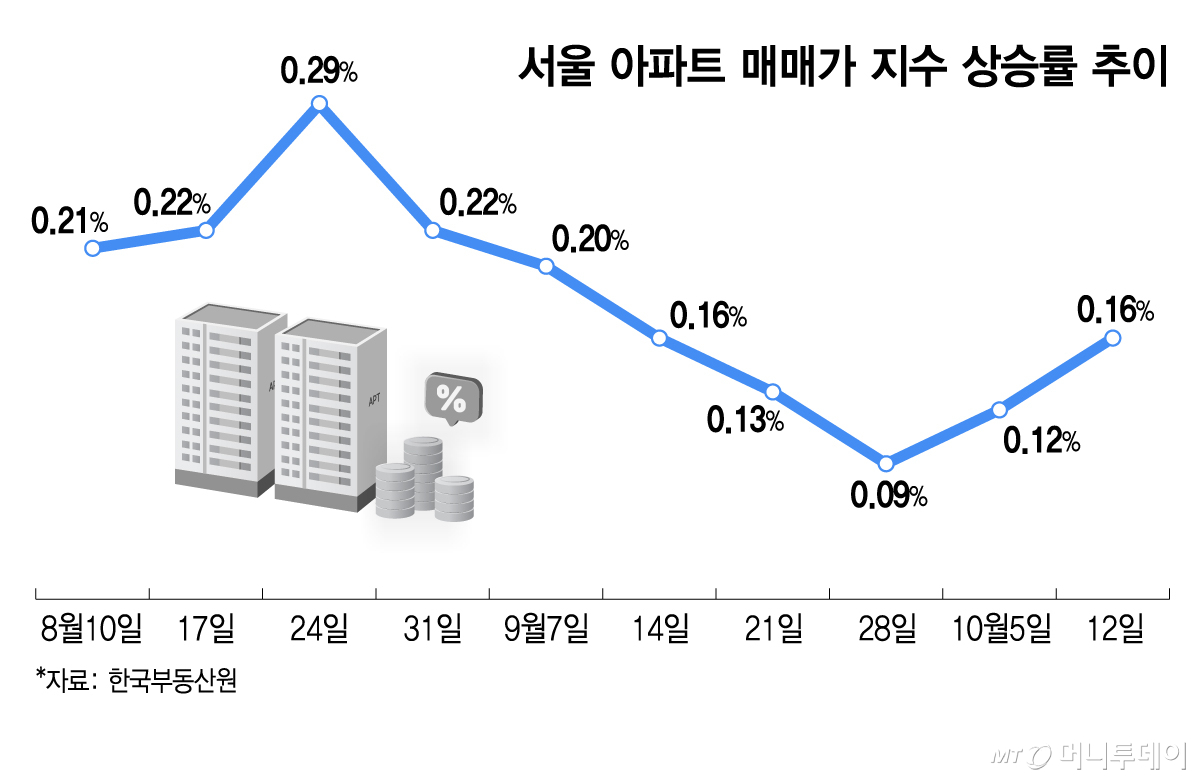
Concurrently, mid-to-lower tier autonomous districts in Seoul absorbed displaced buyer demand. MBC News noted that regional sub-markets such as Seongbuk-gu saw apartment prices jump 16.52% over the twelve-month observation window, alongside substantial gains in areas like Jungnang-gu (0.42%), Seongbuk-gu (0.41%), Seodaemun-gu (0.40%), Dobong-gu (0.39%), and Nowon-gu (0.37%). Furthermore, weekly housing statistics released in October revealed that Seoul’s aggregate apartment price growth rate rebounded from 0.09% at the close of September to 0.12% in the first week of October and 0.16% by the second week of October, securing an 88-week rising streak. Gyeonggi Province also climbed 0.26%, outpacing the previous week’s 0.18%, led by sharp advances in southern nodes such as Seongnam Bundang-gu (0.79%), Gunpo (0.72%), Suwon Yeongtong-gu (0.69%), Hwaseong Dongtan-gu (0.66%), Gwangmyeong (0.62%), Uiwang (0.60%), Hwaseong Byeongjeom-gu (0.56%), Seongnam Jungwon-gu (0.55%), and Yongin Giheung-gu (0.52%).
| Region / District | Recent Weekly Price Index Change | Key Market Driver |
|---|---|---|
| Seoul Average | +0.16% | Sustained multi-week upward momentum across mid-tier sub-markets |
| Gangnam 3 Districts | -0.21% to -0.35% | Extended consolidation phase following heavy regulatory oversight |
| Seongnam Bundang-gu | +0.79% | Expanding buyer demand and localized supply constraints |
| Hwaseong Dongtan-gu | +0.66% | Spillover liquidity from adjacent industrial and tech hubs |
Divergent Perspectives on Regulatory Efficacy and Future Exit Strategies
Official assessments of the intervention remain divided between administrative defense and industry-wide criticism. During a parliamentary audit on October 7, Hong Ji-sun, Minister of Land, Infrastructure and Transport, defended the policy, asserting, Even so, because we implemented the permit system, we kept [housing prices] bundled at this level,
and maintaining that, Housing prices did not go up because of the permit system,
as reported by KBS News. Regarding the extension of the permit system, Hong stated, Looking at the current situation, I think there is a certain level of demand for the permit system.
The Ministry maintains that physical supply constraints during low-construction cycles necessitate continued regulatory oversight.
Conversely, private sector analysts and academic researchers emphasize the unintended structural consequences. Nam Hyuk-woo, a real estate researcher at Woori Bank, observed that persistent liquidity combined with corporate financing programs—such as semiconductor sector employee loan initiatives—has catalyzed speculative expansion into southern Gyeonggi nodes including Suwon, Yongin, Gunpo, and Hanam.

